
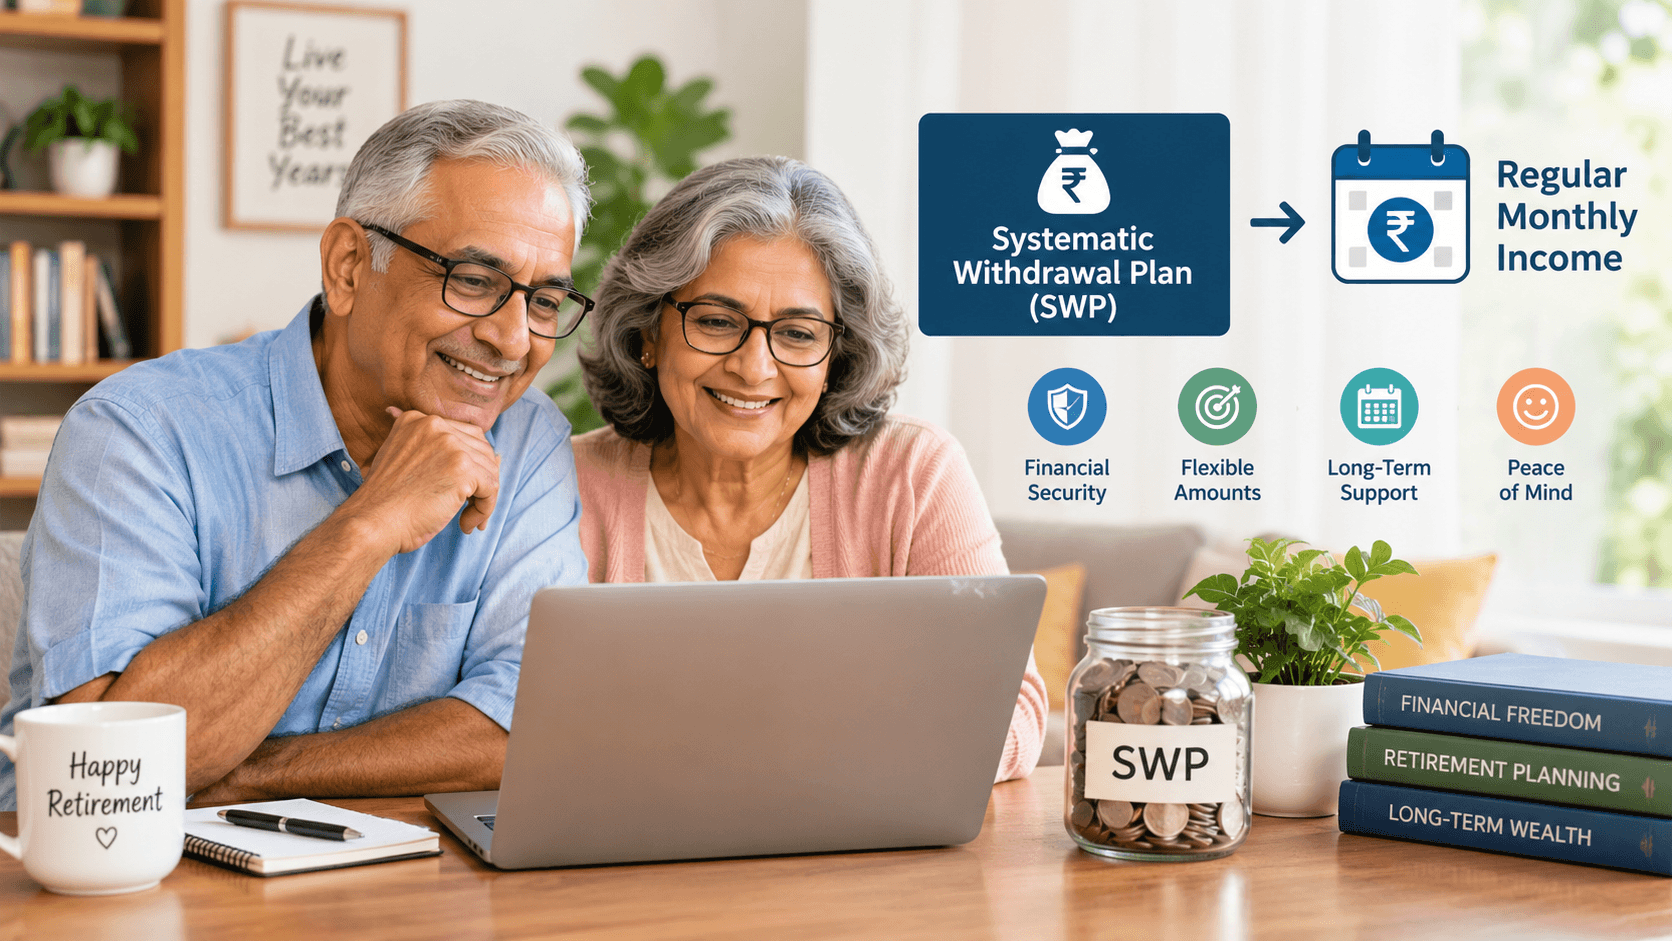
Retirement does something strange to your relationship with money. For thirty or thirty-five years, you focused on putting money in. Now you need to take money out, and the psychology of that shift is harder than anyone prepares you for. Every withdrawal feels like you are shrinking something you spent decades building. That anxiety is real, and it is exactly why a systematic withdrawal plan exists. But most retirees either do not know about SWPs or misunderstand how they work. Spending five minutes on a swp calculator before you restructure your retirement income can save you from mistakes that compound just as powerfully as your investments once did, except in the wrong direction.
What a Systematic Withdrawal Plan Actually Does
Let me strip away the jargon. You have a mutual fund corpus. Instead of redeeming it all at once (terrible idea, for reasons I will get to), you set up an instruction to withdraw a fixed amount every month. The fund house sells just enough units to give you that amount and the rest of your money stays invested, still growing.
The beauty is in what it solves. You get a predictable monthly income without parking your entire corpus in a savings account or fixed deposit earning 6-7% while inflation quietly eats 5% of it. The portion that stays invested in a balanced or equity-oriented fund has a shot at earning more than inflation over time. Your money works even while you spend it.
What a swp calculator does is help you figure out the right withdrawal amount so you do not drain your corpus too fast. Withdraw too much per month and you run out of money at 72. Withdraw too conservatively and you live like you are broke when you are not. The calculator lets you test different scenarios before you commit to anything.
Why Fixed Deposits Alone Are a Losing Game for Retirees
I know this sounds harsh, and plenty of retirees will push back on it. FDs feel safe. The interest shows up reliably. You do not lose sleep over market movements.
But here is what FDs actually deliver after tax. If your FD pays 7% and you are in the 20% tax bracket (which many retirees with pension income are), your post-tax return drops to around 5.6%. Inflation in India has averaged somewhere between 5% and 6% over the past decade. So your real return, the one that actually preserves your purchasing power, is close to zero. Maybe slightly negative in bad years.
That means the pile of money you retired with buys a little less every single year. By the time you are 75 or 80, your monthly expenses have grown significantly but your FD income has not kept pace. This is the slow crisis that nobody talks about because it does not look like a crisis. It looks like gradually tightening your belt year after year until your lifestyle has quietly shrunk around you.
An SWP from a balanced mutual fund does not guarantee higher returns. But it gives your money a realistic chance of outpacing inflation, which is something FDs structurally cannot do for someone in a taxpaying bracket. Use a swp calculator to model what happens to your corpus over fifteen or twenty years under both approaches.
Getting the Withdrawal Amount Right Is the Whole Game
This is where most retirees go wrong. They calculate their monthly expenses, set the SWP to that exact number, and assume the maths will hold forever.
It will not. Expenses do not stay flat. Healthcare costs alone can double or triple in your seventies compared to your sixties. Travel, home maintenance, gifts for grandchildren, things add up in ways you do not plan for.
A safer approach is to set your SWP at about 5-6% of your total corpus annually. So if you have fifty lakhs invested, your annual withdrawal should be around two and a half to three lakhs, which works out to roughly twenty to twenty-five thousand a month. That leaves enough of your corpus invested to keep growing and absorb the occasional bad market year without collapsing.
Run this through a swp calculator with different return assumptions. Try 8%. Try 10%. Try a conservative 7%. See how long your corpus lasts under each scenario. You want a withdrawal rate where your money survives at least twenty to twenty-five years past retirement, ideally longer. If the numbers look tight at your planned withdrawal amount, it is better to know now than to find out at 78.
Tax Efficiency That Nobody Mentions at the Bank
Here is something your bank will never tell you, because it directly competes with their FD products.
When you earn interest on a fixed deposit, the entire amount is taxable as income in the year it is earned. Every single rupee of interest gets added to your taxable income.
SWP withdrawals work differently. Each withdrawal is partly a return of your own capital and partly gains. Only the gains portion is taxable. And if your fund is equity-oriented and held for more than a year, those gains are taxed as long-term capital gains at a significantly lower rate than your income tax slab. The effective tax on each SWP withdrawal ends up being substantially less than what you would pay on equivalent FD interest.
Conclusion
Too many retirees think in terms of products. Should I buy an annuity? Should I stick with FDs? Should I try SWP? The better question is: what monthly income do I need, for how many years, and what structure keeps my purchasing power intact across that entire period?
An SWP is not the only answer. It is one piece, usually the growth-oriented piece, of a broader retirement income design that might also include FDs for short-term safety, a senior citizen savings scheme for guaranteed returns, and an emergency buffer in a liquid fund.
But for the portion of your corpus that needs to beat inflation and last twenty-plus years, an SWP from a well-chosen balanced fund is hard to argue against. Open a swp calculator, test your numbers, and build from there. The worst thing you can do with retirement money is let it sit somewhere “safe” while inflation slowly makes it insufficient.

View 0 comments